• VISIT
    • Experiences
    • Who attends
    • Meet the team
  • CONTENT
    • Key themes
  • SPEAKERS
  • HOSTED MEETINGS
  • PARTNERS
    • Sponsorship prospectus
  • JOIN THE WAITLIST

Fintech Talents

Fintech Talents

Kallyas is an ultra-premium, responsive theme built for today websites.

T (212) 555 55 00
Email: sales@yourwebsite.com

Your Company LTD
Street nr 100, 4536534, Chicago, US


Content

STAY TUNED

Will CBDCs be built on digital identity?

by Laura Camplisson / Tuesday 17 May 2022 / Published in Content, Identity, Opinion, Payments, Regulation
CBDCs and identity

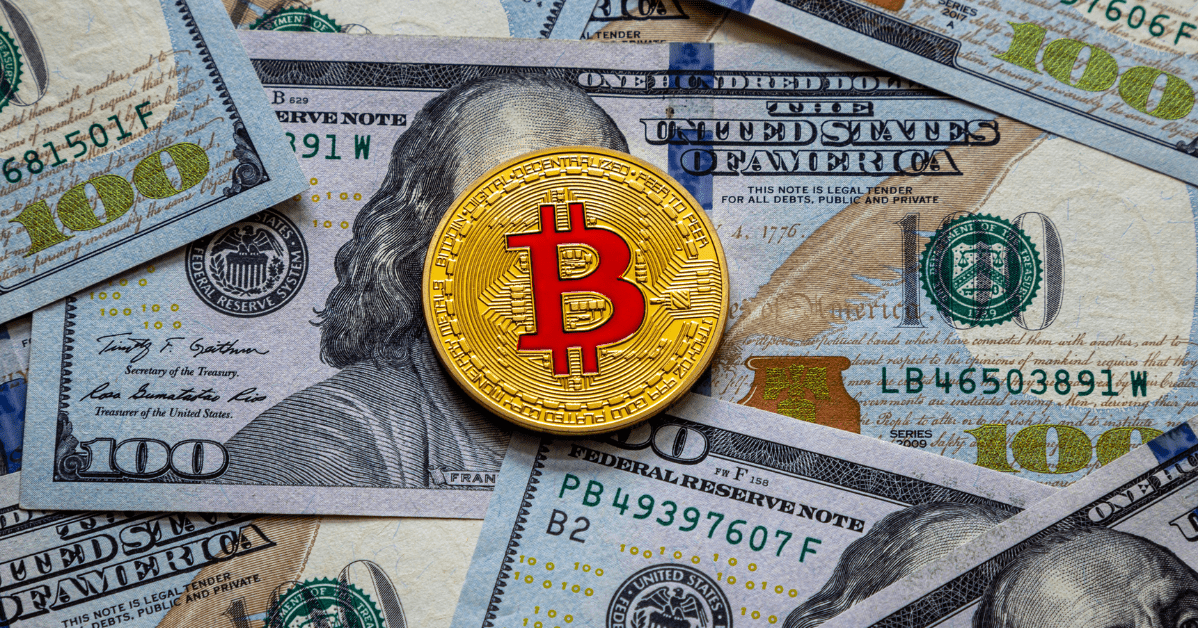
Economists, governments, financial institutions, and crypto players are showing a growing interest in the development of central bank digital currencies (CBDCs).

The term refers to a digital token of a country’s official currency, providing the public with direct digital access to central bank reserves. Issued and regulated by a national monetary authority or central bank, a CBDC is fully backed by the issuing government.

As of March 2022, 9 countries have officially launched a CBDC, and 87 countries are considering doing so. As CBDCs rapidly expand in scope, complex questions surrounding privacy and digital identity are brought front and centre.

What are the proposed benefits of CBDCs?

So, could central bank digital currencies be the future for money? We can already transfer money digitally, but a CBDC transaction wouldn’t need to pass through different banks and could happen instantly on a single digital ledger.

Proponents of CBDCs argue this will eliminate many of the high costs and inefficiencies of international payments and allow monetary architectures and policies to be simplified. Another alleged benefit is the promotion of greater financial inclusion by providing unbanked individuals with access to mobile money.

Arguably the longer central banks take to bring digital currencies to market, the more opportunity for private companies to issue digital cash alternatives at inflated costs, and which exclude vulnerable segments of society. Especially if any private company were to gain a monopoly.

The question of privacy and identity

For CBDCs to be universal and accessible to everyone, they must be privacy preserving and not linked with an individual’s record or credit history. But as with any financial transaction, there also comes the obligation to prevent the use of CBDCs for money laundering and fraud.

As a result, customer due diligence and KYC procedures will prevent CBDC accounts from being fully anonymous. Central banks or intermediary financial parties will face the task of monitoring customers and transactions. And as all transactions will be recorded on a digital ledger, it should prove easier for authorities to detect illicit activity.

The challenge is collecting the necessary personal data to prevent financial crime, but without allowing this data to contribute to exclusion. Will central banks have complete control potentially eroding the privacy of citizens? Will trusted intermediaries be involved? How much control will account-holders have over who is granted access to their data?

A retail or a wholesale model?

They way in which digital identity verification procedures will be managed, will be heavily impacted by whether a retail or wholesale model is adopted. In a retail model, CBDC customers will have direct access to the digital currency through an account with the central bank. The central bank will then have the role of onboarding customers and performing KYC and identity checks.

In the wholesale model however, banks and financial institutions would administer CBDC accounts. Arguably, this would be more feasible from an identity management perspective, as retail banks (unlike central banks) are already equipped to manage identity verification on a major scale.

This would be a less significant departure from the current system operating in developed economies, but perhaps would be a missed opportunity for digital ID. By integrating or building digital ID schemes to support CBDCs, central banks could effectively manage KYC processes and advance the development of digital identity. An identity infrastructure based on accessibility, ease of use and privacy protection, would reflect the nature of digital currencies and advance the digital ecosystem significantly.

Will ID schemes play a role in the delivery of CBDCs?

One way or another, it seems clear CBDCs will have to be linked with digital identity to manage risk and secure payments. And the status of a national identity ecosystem could be a key determining factor in whether a wholesale or retail CBDC model is adopted.

In Sweden for example, the well-established Bank ID system is administered by a network of Swedish and Scandinavian banks and is used by 95% of the population to access public and private sectors. Leveraging this already strong digital ID scheme could be a driver for the Swedish Riksbank to adopt a wholesale model for the e-krona currently being explored.

Countries less advanced in the development of digital identity or in digitisation efforts in general, might find adopting a retail model for CBDCs could present a huge opportunity to promote greater inclusion and advance financial digitisation through a broader digital ID-based system.

As CBDCs continue to evolve, it is important to consider how our personally identifiable data is managed by various parties, and who we would ideally trust with this in the future. Governments, financial institutions, tech players and end users should consider the impact for digital identity as the monetary systems of the future rapidly emerge.

_________________________________________________________________________________________________________________________________

The conversation continues at FTT DeFi, on 12th July 2022, with sessions powered by Future Identity, exploring how identity systems will evolve as as the internet, the economy and our lives become increasingly decentralised.
Tagged under: CBDC, Crypto, DeFi, digital transformation, Payments, Splash, Technology

Recent Posts

  • Nobody is asking their bank for a bot. Snappi Bank on how AI supports a more human experience

    At FTT AI Transformation this summer, we spoke ...
  • Building AI that works at scale with Savita Nanda from Rabobank

    AI adoption in financial services is moving bey...
  • Where AI is taking SME lending next? with Mario Husha, CTO, Lovey

    AI is moving at a pace that can leave regulatio...
  • Margus Simon, Komerční Banka: The risk of AI? Not innovating fast enough

    We sat down with Margus Simon Chief Digital Off...
  • From resistance to excitement – How to make AI work with Lucile Flamand

    We sat down with Lucile Flamand for a chat abou...


  • Home
  • Call for speakers
  • View all events
  • Fintech Talents events
    • FTT Fintech Festival 2026
    • FTT AI Transformation 2026
    • FTT Mutuals 2026
    • FTT Fintech Festival North America 2026
    • FTT Lending 2027
    • FTT Payments 2027
    • FTT AI Transformation 2027, powered by Covecta
  • FTT Embedded Finance & Super-Apps events
    • FTT Embedded Finance & Super-Apps Europe 2027
    • Customer Alpha Europe 2027
  • Future Identity events
    • Future Identity Festival 2026
    • FID Fraud & FinCrime – Fall Europe 2026
    • FID IAM – Fall Europe 2026
    • Future Identity Festival North America 2026
    • Future Identity Finance Europe 2027
    • FID Fraud & FinCrime – Spring Europe 2027
    • Future Identity Customer Europe 2027
    • FID IAM – Summer Europe 2027
  • Past events
    • Breakfast briefing: Commercial onboarding 2026
    • Webinar: Closing the Confusion Gap 2026
    • FTT Financial Services Futures 2025
    • Fraud prevention & customer experience webinar 2025
  • Content
    • All Content
    • Interviews
    • Opinion
    • Videos
    • Digital Reports
  • VC INNOVATIONS – Accelerated Marketing

GET IN TOUCH

T +44 203 835 2829
Email: marketing@vcinnovations.co.uk

LONDON
2 Bloomsbury Place, London WC1A 2QL, UK
Open in Google Maps

NEW YORK
477 Broadway, 2nd Floor, Suite 1033, New York, NY 10013
Open in Google Maps

QUICK LINKS

  • Home
  • About VC INNOVATIONS
  • Events
  • FAQs
  • LinkedIn
  • Twitter
  • YouTube
  • Instagram

CPD ACCREDITED

RECENT POSTS

  • Nobody is asking their bank for a bot. Snappi Bank on how AI supports a more human experience

    At FTT AI Transformation this summer, we spoke ...
  • Building AI that works at scale with Savita Nanda from Rabobank

    AI adoption in financial services is moving bey...
  • Where AI is taking SME lending next? with Mario Husha, CTO, Lovey

    AI is moving at a pace that can leave regulatio...
  • Privacy Policy

© VC Innovations 2026. All Rights Reserved.


TOP
 
Tech & solution providers: Save £300 before 23rd October 2026
BOOK NOW
Groups of four or more receive a 10% discount
 
 
Tech & solution providers: Save £300 before 23rd October 2026
BOOK NOW
Groups of four or more receive a 10% discount
 
 
Tech & solution providers: Save £300 before 23rd October 2026
BOOK NOW
Groups of four or more receive a 10% discount
 
 
Tech & solution providers: Save $700 before October 16, 2026
BOOK NOW
 
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behaviour or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behaviour or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
Download Prospectus Form


Get involved


Press & Media Pass


Get involved


Press & Media Pass


FTT Fintech Festival 2026 - See who attends


FTT Fintech Festival 2026 - See who attends


Download the 2025 agenda


Download now


hbspt.forms.create({
portalId: “5855210”,
formId: “9eade2ea-7e37-4c7b-9f26-7231a3531732”,
region: “na1”
});

Download now


Download now


FTT AI Transformation 2025 - Download previous attendee list


FTT Payments 2025 - Download previous attendee list


Get involved


Get involved


Get involved


Press & Media Pass


FTT Mutuals 2025 - Download previous attendee list


Get involved


  • VISIT
    • Experiences
    • Who attends
    • Meet the team
  • CONTENT
    • Key themes
  • SPEAKERS
  • HOSTED MEETINGS
  • PARTNERS
    • Sponsorship prospectus
  • JOIN THE WAITLIST